
Key takeaways:
- MSR values are strong. Citing Mortgage Capital Trading, Chris says bulk MSR portfolios are trading at about 4.5x to 5.25x servicing fees. He puts historical multiples at roughly 2x to 3x. Government MSRs with no delinquencies and rates below 5.5% are trading around 3x to 4x.
- The environment helps servicers. Servicing operating income is stable, delinquencies are historically low (though ticking up), and higher short-term rates can improve returns on escrow and custodial balances.
- Servicing is expensive and getting more so. Chris cites MBA data showing about $176 per loan per year rising to $185, which is about 5% in a year and about 15% since 2016. About two-thirds of that cost isn’t default-related.
- AI helps, but use it carefully. Chris sees real long-term savings but warns about upfront cost, compliance, and AI-driven decisions about borrowers. He says the bigger opportunity is data infrastructure that shows recapture and refinance propensities and default risk across the book.
- Retaining servicing is a build-or-buy decision. Chris says there’s no single minimum volume. It depends on your servicing maturity, and many lenders take a hybrid approach. Compliance, investor reporting, remittance, and reconciliation are where mistakes get expensive.
- Sub-servicing can cut costs and add flexibility. Chris says lenders can see roughly a 30% cost reduction, avoid staffing up and down, and buy or sell MSRs without capacity worries.
- Private label protects your borrower relationship. At DMI, everything the borrower sees carries the lender’s brand, including calls, statements, and digital tools. Chris argues that this, plus targeted loan-level messaging and good service, drives recapture and referrals.
- Technology plus people. DMI manages about 1.5 million loans across all 50 states for close to 300 clients. Chris says it emphasizes easy self-service, quick access to a human, and giving reps full borrower history and the company’s policy knowledge so more calls are resolved on the first try.
Mortgage servicing is more than just collecting payments—it’s a powerful opportunity for lenders to build long-term revenue, strengthen borrower relationships, and create a competitive advantage. In this Hot Topics, David Lykken welcomes Chris Torres of Dovenmuehle Mortgage (DMI) to explore why retaining mortgage servicing rights is becoming an increasingly attractive strategy for lenders. They discuss the financial benefits of servicing, rising operational costs, the advantages of partnering with a subservicer, and how artificial intelligence and data analytics are transforming borrower engagement and retention. Chris also shares valuable insights into selecting the right subservicing partner, managing compliance risks, and leveraging technology to improve efficiency without sacrificing the customer experience. Discover why a well-executed servicing strategy could be one of the most valuable long-term investments a mortgage lender can make.
Transcript:
Welcome and meet Chris Torres (00:00)
David: Listeners, we don’t talk as much as we probably should about the importance of loan servicing, and we’re going to get into that today with our special guest, Chris Torres of Dovenmuehle, also known as DMI, as we refer to it. Chris, so good to have you on the podcast.
Chris: Thank you very much, David. It’s great to be here. We really appreciate the opportunity to contribute some talking points about servicing.
David: It’s an important topic. You recently wrote an article that was published by the MBA, I guess last year, but it was really good. You highlighted the long-term value of building servicing infrastructure, how the decision to sub-service is critical in that step, and some key considerations. That’s what I’m interested in getting into. But let’s start with the market trends you’re seeing that are making servicing a compelling argument again.
Why servicing is compelling again: MSR values and market trends (01:05)
Chris: Of course. I think that’s a great place to start, David. Recently, looking at the bulk MSR market, and I’m going to cite some information from Mortgage Capital Trading, who do a great job with bulk trades and assisting people with their mortgage servicing rights portfolios, you’re seeing multiples for bulk portfolios trade between 4.5x and 5.25x of servicing fees. That’s a pretty compelling argument right there, and it provides a lot of liquidity.
David: Give us the historical significance of that, Chris. Where does that land on the continuum? Is that historically high or low?
Chris: Absolutely. On average, multiples were probably much lower, let’s say in the two to three range. So to see them now exceeding five is a pretty compelling argument. A lot of what’s happening is that people are tuning in to the fact that you’re pricing in the opportunity to recapture or retain those valued relationships. It’s not only the profile and characteristics of the mortgage servicing rights, it’s also the opportunity that lies within them.
As a matter of fact, even government MSRs with no delinquencies and interest rates below 5.5% continue to trade between 3 and 3.75, even 4. Those government loans tend to have a more expanded credit box, so to see that kind of momentum in the multiples, even for government, really paints a picture of where we are and what the market is saying.
Beyond that, servicing operating income is stable. You also have a Fed funds rate that has increased. The Fed just raised rates last week, and that can translate into benefits in managing escrow accounts and custodial accounts, making sure you get the full economic benefit of those funds. We’re also still in a historically low delinquency environment. Delinquencies are ticking up a little and we’re keeping a close eye on that, but compared to ten or fifteen years ago they’re very tempered. All of that creates a great environment to start retaining servicing and to create a long-term revenue stream for your organization.
What’s driving servicing costs (03:40)
David: Let’s look at servicing costs. What are some of the drivers?
Chris: That’s a great question. The MBA publishes some great data that shows historical trends and breaks it down between performing and non-performing loans. Generally speaking, it’s been hovering around $176 per loan on average, annually. They recently came out with a chart, I think a couple of months ago, showing that number has increased to $185 all in. That’s about a five percent increase in the most recent year, and it follows the trend of the last two years. If you look at the last ten years, since 2016, that translates into a 15% increase.
As for the drivers, the MBA spelled them out for us: servicing systems, customer service, and specialized functions tend to be some of the biggest, pushing costs up gradually. Notably, two-thirds of those costs are non-default related. Even the day-to-day cost of servicing non-delinquent loans is putting pressure on servicers.
It’s an interesting topic, because there’s been a lot of technology that’s come into play, but you’re not seeing a lot of those returns materialize, even with the technology available today. Servicing is very resource intensive. You need to make sure you’re right-sizing the infrastructure, the overhead, and even the human capital in your organization to do it correctly. So with all of that, there’s a compelling argument to retain servicing, but how do you do it optimally? How do you do it in a controlled manner that provides efficiencies downstream for your organization?
Can AI lower servicing costs? (05:55)
David: When you’re looking at these drivers, and there’s been a slight increase, has AI entered into this and started putting downward pressure on any of it? We’re seeing AI enter every other aspect of the mortgage industry.
Chris: That’s a great question, and I do think we’re at the advent of AI right now. There are a lot of powerful things going on. One consideration is the cost to acquire some of these tools. It’s expensive to roll out across your organization, so that initial investment matters. Over time, I do think AI applications and use cases will help drive costs lower, because manual functions, and a lot of what I was saying about human capital, will be automated and potentially replaced.
But there’s still the question of how to use AI strategically so that you’re solving real-world problems. I think everybody’s rushing to solve for low-hanging fruit, and I’d advise being cautious about how that plays out in your organization. Since we’re at the advent, there are risk and compliance considerations. If you’re going to let AI make decisions for borrowers or clients, you have to be very much on top of that. You don’t want to leave it to its own devices. You want to understand how these models work, how they’re trained, how they’ll perform, and how they’ll ultimately serve your customers.
Personally, I think the biggest opportunity in servicing is your data infrastructure: how you analyze, uncover opportunities, gain clarity, and get to action much more quickly on what lies within your portfolio. If you don’t have the right data infrastructure, and the tools to peel back the onion and say, “These are our risks and these are our opportunity areas,” then I think you’re missing the mark.
Since we’re talking about recapture and retention, if you start funneling your servicing data through some of these AI models, they can give you very powerful outcomes. You can see, within your own book, the propensity to take out an equity mortgage or a refinance. You can mitigate risk, get ahead of propensity to default, and understand borrower behavior. Then you can meet your borrowers where they are and add value, so when they’re ready to make another decision, you’re the first call they make rather than going to a competitor.
Build, buy, or hybrid: key considerations before retaining servicing (08:55)
David: You started touching on key considerations already. What other considerations should lenders and prospective servicers weigh in deciding whether to retain servicing?
Chris: I always think about it from the top down, and it goes back to your organization’s values and strategy. If you want to invest in servicing, you’re faced with a decision: do I build all of this out, or do I buy it? Are there vendors or partnerships I can take advantage of to maximize it? It doesn’t have to be one-size-fits-all or black and white. Many people take a hybrid approach: certain aspects of servicing they outsource, certain aspects they keep in-house.
At the heart of it, you have to understand why you want to do it. If you’re going to be a servicer, you need to do it correctly and have the resources in place to avoid compliance risk. It only takes one penalty or enforcement action to feel the economic brunt of it, and you don’t want to be in that situation. Sometimes compliance is overlooked.
The hidden costs: compliance, staffing, and investor requirements (10:00)
David: Especially in servicing. It gets so expensive if you overlook it. I think back to the CFPB days. The last statistic I saw was that 80% of the complaints phoned in or given to the CFPB had to do with servicing.
Chris: Absolutely. Right there you see a big area of risk. Who’s answering the phones? How are you answering them? How quickly? Are you keeping the borrower’s best interest in mind? Are you giving them opportunities to navigate financial hardship? That’s the customer service piece. And when you peel that back, you’re asking how many reps you need, how many FTEs interacting with borrowers. That’s just a fraction of it. Then you layer in telecom costs, data infrastructure costs, even mailers, postage, and notices. All of that gets embedded in the recurring cost of day-to-day servicing, and people have to be aware of it.
On the back end, you also have to think about investor relationships. If you’re going to be a seller-servicer with the GSEs, they have a very robust framework to qualify you and approve you. Then you have the special requirements of each investor: reporting, remitting, reconciliation, the different remittance methods. One hiccup there can put you in a position where you have to buy back the loan. You want all of that locked up so you can make the most of your investment.
I do think that’s a compelling argument to retain servicing, too. If you become a seller-servicer, you create an additional revenue stream for your organization, and you stay front and center with your borrowers even if the investor owns the credit. Even if Fannie or Freddie owns the credit, you’re still compensated for servicing those loans. If you do it correctly, it can be a very nice piggy bank that you accumulate over the years.
David: It’s a wonderful annuity, an asset that continues to grow in value as you add to it.
How much volume makes retaining servicing worth it? (12:35)
David: At what level of funding does it really make economic sense to start retaining?
Chris: I’m glad you asked. I’d like to say there’s no silver bullet. It’s more a decision about where you are in your servicing maturity. At Dovenmuehle we work with clients both big and small. Some have portfolios in excess of hundreds of thousands of loans, and some have only a couple hundred. In each case, these organizations are making their own decision: “We don’t want to take that on. We don’t want to worry about putting out servicing fires. Instead, we want to focus on our product mix, on what the market is telling us, and on meeting our borrowers where they are with value-added solutions.” So it’s a more complex question than a single number.
David: A complex answer to a complex question. But when you start working with someone, you actually advise them and help them do that analysis.
Why sub-service: expertise, 30% savings, and flexibility (13:45)
Chris: Absolutely. That’s one of the key benefits of working with a sub-servicer: you get operational expertise and the capacity to do all of it correctly. There’s the matter of not knowing what you don’t know. Once you start talking to people who do this day in and day out, you realize how much you need to invest in, or how much you need to solve for, and that’s where a sub-servicer comes in.
Going back to cost, on average if you partner with a sub-servicer, you could enjoy approximately a 30% reduction in costs. You also don’t have to worry about staffing up and staffing down. If you’re in an active trading space with your MSR portfolio, you can really set it and forget it. Whether you want to sell or acquire new MSRs, you don’t have to worry about what it will take to take that on. And if you’re a portfolio lender, you don’t have to worry that you can’t scale, or can’t add a product, or can’t solve something for a borrower because you don’t have capacity on the servicing side. You’re getting a major lift: a turnkey operation from an experienced organization, so you don’t have to worry about servicing and can take care of the rest.
Private label: protecting your brand and your borrower relationship (15:25)
David: I’ve been in DMI’s offices, and I was so impressed with the systems you have in place. The cost of setting something like this up is a barrier that doesn’t make sense unless you reach a certain scale and size. Is a sub-servicer the only option someone should consider? Describe the benefits. You already touched on helping them decide when to do it, how much to hold, and when the trading opportunities are. Another benefit is that they get to market back to that customer, and they can do that through you with the different levels of service you offer. Talk about that.
Chris: Absolutely. That’s where you have to evaluate who your partner will be for the long run. We actually have a whole white paper on this, and I’d love to share it with anyone in the audience who reaches out. It goes into how to evaluate a sub-servicer and find the right fit.
At Dovenmuehle we have a private label sub-servicing program, so everything we do has the lender’s brand front and center. That’s a very powerful thing. If you’re partnering with a sub-servicer, you want to be sure they won’t compete for your valued borrower relationships. It takes a long time to establish those, and having someone else servicing and potentially competing for them can be troubling. So from the get-go, make sure your brand is visible: across phone interactions, on fully branded billing statements, and across every digital piece, whether a website or a mobile app. Borrowers should know that, regardless of the systems they use, it’s their lender helping them, so when the time comes they’ll reach back out.
Targeted, loan-level messaging that’s relevant to each borrower is also paramount, because what’s right for one borrower may not be right for another. If you can get the relevant details to the right people at the right time, you’ll enjoy the benefits of that lending relationship two, three, fourfold. Then there’s word of mouth. If borrowers find you’re doing a good job for them, they’re more likely to tell their friends. Referrals are a very powerful thing, especially for loan officers.
On the back end, again on the compliance side, you want borrowers to feel supported and not fall through the cracks with their questions. They need avenues to get support after natural disasters and in cases of financial hardship. How easy do you make it for them to apply for hardship assistance and get the help and counseling they need? All of that is imperative.
You also want a sub-servicer who understands that these are your assets. If you’re a portfolio lender, they need to collaborate with you to understand your guidelines, follow them, and offer borrowers options based on them. For other investors, like Fannie, Freddie, and Ginnie, you have to follow their respective guidelines. That comes back to expertise. Having experience with those investors means you don’t have to worry about what options your borrowers will see.
Technology and the borrower experience at DMI (19:05)
David: Technology has played such an important part in the sub-servicing relationship and execution. Talk about some of the strategies you’re employing. Your phone system is amazing: when to call, how often to call. It’s getting more and more tailored to the borrower’s needs, to keep loans current. That’s a big part of the DMI story.
Chris: Thank you for the recognition. It starts with making it easy to self-serve the commonly asked questions. You’d be amazed. A lot of people call in just to make sure their payment went through. With batch processes you sometimes don’t see payments post right away. So being able to customize the initial call tree, so a caller can say, “I have a quick question, I just want my answer and to move on with my life,” is step one.
Step two is how easy it is to get a customer service representative on the phone, a human they can have a dialogue with, who can understand what’s going on with their mortgage. That goes back to AI. AI is getting very sophisticated, and I’m sure there are great AI agents doing great things with calls. But Qualtrics publishes metrics on consumer sentiment, and consumer sentiment toward AI in customer service has cratered. A lot of people have found it frustrating. I don’t know if you’ve had interactions with AI call agents yet, but it can be very frustrating.
David: It’s so true. What’s the size of your portfolio? I think you’re one of the largest servicers, or sub-servicers, in the nation, are you not?
Chris: We are. We’re managing 1.5 million loans right now, so we’re touching a vast number of borrowers across all 50 states every day. Going back to your technology question: once you connect someone with a live agent, the next question is how empowered that agent is to answer. That’s where a strategic use of AI comes in. At DMI we’ve built a whole ecosystem to empower our customer service representatives to answer very detailed questions. We connect them with our entire knowledge base. They have access to all the borrower and loan information, trends, call histories, hot buttons, red flags, and green flags. We also connect all of our policies, procedures, and operational experience, so when a rep is interacting with a borrower, they can get into the finer details rather than passing the buck.
It all comes down to first-call resolution. If a borrower gets what they need on the first call, that’s a happy borrower, they get the word out, and you retain the relationship. And we’re doing that on behalf of close to 300 clients. That’s a very powerful place to be, in terms of meeting different requirements for different borrowers at the right time.
How to reach Chris Torres (22:55)
David: How can people reach you, learn more about sub-servicing, and get into a more detailed conversation specific to their needs?
Chris: You can find us at our website, Dovenmuehle.com. There’s a form you can fill out, and we’ll give you a call back promptly. You can always reach me personally, too. I’m on LinkedIn, and I’ll make sure my email and phone number are listed for anyone listening who wants to get in touch. I’d welcome the opportunity to have a conversation at your convenience.
David: Good. Chris, thank you so much. Congratulations on the success. You’ve been at Dovenmuehle for a while. You’re not new there, so you have a lot of experience, and I encourage people to talk to you.
Chris: Thank you, David. I appreciate the opportunity to be here and share a little information about servicing.
David: Great job. Good to have you on. Folks, check out the link to the article that we’re putting in the show notes, along with Chris’s contact information. Thank you for listening to this important podcast. Share it with others, especially if you’re looking to get into servicing. Dovenmuehle is a place I refer all of my clients, and that’s a pretty strong endorsement. Thanks, Chris. I look forward to having you back soon.
Chris: Thank you, David. I appreciate it. I look forward to coming back.
Important Links and about guest:
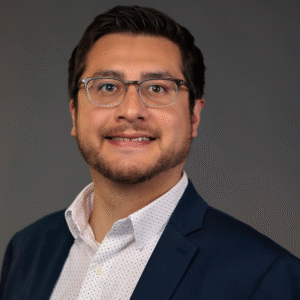
Chris Torres is Vice President, Business Development for Dovenmuehle, headquartered in Lake Zurich, IL. Chris joined Dovenmuehle in 2021 with a background in financial technology and 12 years of experience in the capital markets and commercial banking sectors. He fosters servicing partnerships with lenders nationwide, helping them enhance operations while reducing risks. Chris holds a bachelor’s degree in business administration with an emphasis in finance from the University of Colorado Boulder and joins Dovenmuehle from S&P Global Ratings’ U.S. RMBS team.